Déjà vu
Hey Bank, You launched that industry first AI powered decisioning suite. You launched your first AI-enabled digital branch. Your entire competition announced exactly the same. But to the customer it is déjà vu, playing on a loop, every few years.
We heard the same noise for anywhere banking, internet banking, for mobile banking, then for those dumb branch robots. You did it again for super apps. Meanwhile your IVR is still a fossil from 1998. Your account opening still can’t resolve a simple deviation. Your business analysis is still copy-paste, earlier from the web, now from an LLM. And yes, you still mis-sell those third-party products.
This noise works in a launch event, a board presentation, a press release, a LinkedIn post. It may even make the bank look progressive. What it does not do is answer the rather mundane question the customer is asking: Can I get my work done without fighting your process?
That is the only question that matters. Not whether the bank has adopted a particular technology. Not whether the bank has kept up with the vocabulary of transformation, innovation, digital-first, AI-first, paperless, seamless, frictionless, or whatever the season demands.
The customer never experiences your technology. The customer experiences the effort it takes to get work done.
Fifty out of sixty-six
A few years ago, I was part of a diagnostic review of a bank’s technology strategy. The bank told us, with justified pride, that it had 66 initiatives running to modernise itself. On paper that is a bank in motion with a full transformation pipeline.
When we reviewed these initiatives, 50 of them sat in or around payments. All were useful. But all were incremental, necessitated by ecosystem and regulatory changes. These were being adopted by every bank. Then there was the usual experimental garnish too, a blockchain idea, a VR-led marketing concept, things that look good in a steering committee deck and have little contact with any customer’s actual problem.
In essence it was a catch-up list. The bank was already late. The catch-up game was being presented internally as cutting-edge transformation strategy. It was solving some problems of compliance and competitive pressure. It wasn’t focused on solving customer experience.
The bank had an ambition to become digital. It did not have an ambition to become easier.
Reel bank, Real bank
Banks modernise the happy path, because the happy path is visible, measurable and campaign friendly. But happy paths come with ifs and buts.
Open an account in 30 minutes if every document is perfect. Make a remittance in seconds if all details are correct. Sanction a loan in an hour if the rigid parameters match. Complete KYC if every database agrees. Issue a card at the airport if the bureau profile is unambiguous.
The line before ‘if’ solves something. But the real problem hides after these ifs.
Customers do not live inside standard journeys. People change addresses and mobile numbers. They change mandates, nominees and operating instructions. They move from minor to major. They add and remove joint holders. They deal with deceased accounts. They inherit relationships, restructure loans, dispute charges, and discover that their digital and AI powered bank is still in the previous decade. The real bank appears when the customer needs it to handle a change.
In our family we had to convert a minor account to a major account with one of the country’s largest banks. A child becomes an adult, the operating instructions change, documentation is refreshed. It is the most predictable event in a banking relationship, and known from the day the account was opened. My years in banking didn’t help. Form after form. Document after document. Clarification after clarification. That bank had apps, campaigns, a modern branch and even a dedicated RM. It took months still.
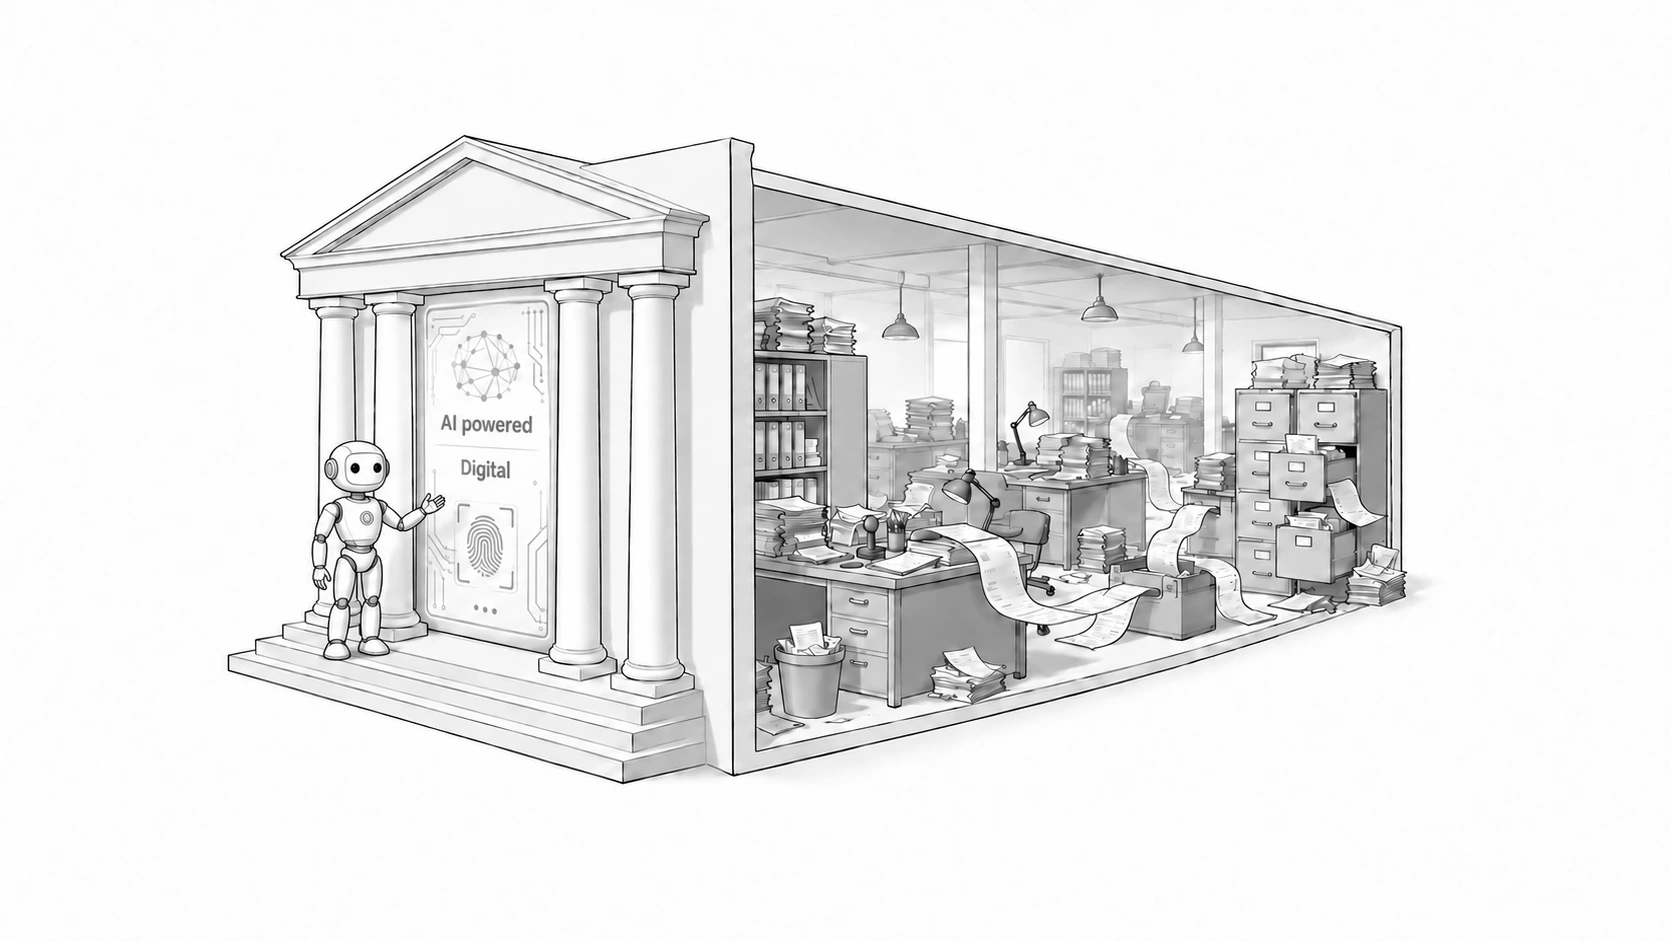
The digital, modern reel bank was on every screen. The old archaic real bank was in the paperwork.
The choice to make noise on technology is perfectly rational and well incentivised. This skew towards quickly winning the happy path customer and with less attention to deviations and servicing is the reason for the gap between how a bank sounds and how it behaves.
Why banks do this anyway: Biases and Incentives
It would be lazy to put this down to vanity or to assume that banks don’t work on improving processes. It would be presumptuous to say they don’t care about customers. They do, sometimes.
The problem is not technology. It is that technology is treated as a marketing asset rather than a real backend resolver, and the incentives inside a bank reward the noise. A board counts initiatives, budgets and go-live dates. It cannot count friction, because nobody instruments friction. A rating agency will ask about capital adequacy. It will not ask how many customers gave up after being asked a third time for a document the bank already holds. An analyst call has a slot for NIM and ROA, the AI roadmap and digital strategy. It has no slot for account mandate change process. So, the inadvertent incentive is to invest in exciting ‘digital’, ‘industry first’, ‘AI-led’ compared to fixing of mundane servicing processes.
At the operational level the measurement bias is towards acquisition. Anything that shows improved acquisition is seen as the real tech initiative. Every lead drop-off is tracked, attributed and reviewed. Servicing, on the other hand, gets measured only when it becomes a complaint. A signatory addition has no funnel. A nominee change has no dashboard. A re-KYC that bounces between the branch and the back office has no owner and no clock. Ask most banks for the median elapsed time on their twenty most common service requests and the answer is likely to be hazy, because the data is either not collected or not properly collated.
Banks do measure themselves on Conversion Rate, Turnaround time (TAT), cost to serve, and digital adoption. These are valid measures. The problem is that these are measured stage by stage, and the customer does not necessarily live in process stages. Much of these metrics can be gamed by simply varying the start and end lines.
The loan was approved in a day. But disbursement then took four rounds of re-documentation. The approval TAT still looks excellent.
Account opening was instant and fully online. Adding a second signatory to the same account took five weeks. The onboarding metric remains perfect.
The card was issued remotely with no branch contact at all. Re-KYC on the same card required a branch visit. The acquisition journey scores 100% for digital end to end.
Of course speed matters and digitisation in each case helps. The bank was fast but in none of them was the bank timely. Speed is how quickly a narrowly defined internal milestone is completed. Timeliness is whether the customer got the outcome when they needed it. A bank optimised for speed can still be reliably late.
First time right (FTR) is not new to banks. They talk about it. They dashboard it. And then the improvement strategy boils down to an employee training on getting the customer to sign in the right places.
This bias is further enhanced due to lack of depth in process design and more tangibly in the product note. Most product notes are written as a checklist of approval criteria. Who qualifies, at what score, at what price, against what security, up to what limit. Edge cases, servicing and deviations at best get a paragraph or two.
As a result, when things are even slightly off the template, the organisation struggles. The customer suffers. Without a pre-defined basis, the deviation approver asks for comfort in the form of another document. The RM goes back to the customer. Improvements are after-thoughts, reaction to customer escalations. This is the loop, and every dashboard files it as ‘document awaited from customer’ and brushing the real cause under the carpet.
What to measure
A happy path of approval conditions is not a process design. Until every deviationin the product and process has been thought through and documented, no technology intervention will resolve the friction.
So, the first step is to build right metrics, because in a bank nothing gets attention until it gets counted. Below is the list of a few directional pointers.
| Measure | What it counts |
| Touches per completed request | Every interaction the customer had to initiate, from first ask to closure. |
| Elapsed time on the customer’s clock | Calendar days from first request to final outcome. Median and 90th percentile. |
| Repeat-document rate | How often the bank asks for a document it already holds. (this can include data redundancy- same detail sought again and again) |
| Post-approval document additions | Documents asked for after the first decision, per case. |
| Deviation coverage | Share of deviations encountered outside the anticipated scenarios. |
| Reopen rate | Share of closed requests where the same issue comes back within a month. |
| Channel consistency | Whether branch, call centre, app and back office give the same answer to the same question. |
| Service catalogue coverage | Share of service journeys, as distinct from product journeys, assessed and redesigned in the last three years. |
Put these in front of a board once a quarter and the transformation priorities will rearrange themselves.
Hey bank, become easier
Use technology. Use it deeply, and use it wherever it removes repetition, shortens waiting, clarifies who is responsible and makes service more humane. Banking is dynamic and needs better systems, cleaner workflows, stronger data and sharper controls, and it needs them urgently.
So when I say I do not care about your technology, I mean the customer should never have to notice it. Used well, it disappears into the solution. It shows up as a form that was not repeated, a document that was not asked for twice, a request that was not passed from one desk to another, and a deviation that was not treated as a system failure. None of that makes a jazzy press release. Then again, no bank loses a customer over a missing AI feature. Technology is not the shiny glass facade. It is the hidden, efficient plumbing behind it.
The claim worth making is not that you are digital or AI-led. It is that a service request now closes in one visit, and that when something changes in customer’s life, you do not turn it into a project.
Hey bank, make banking easier.
